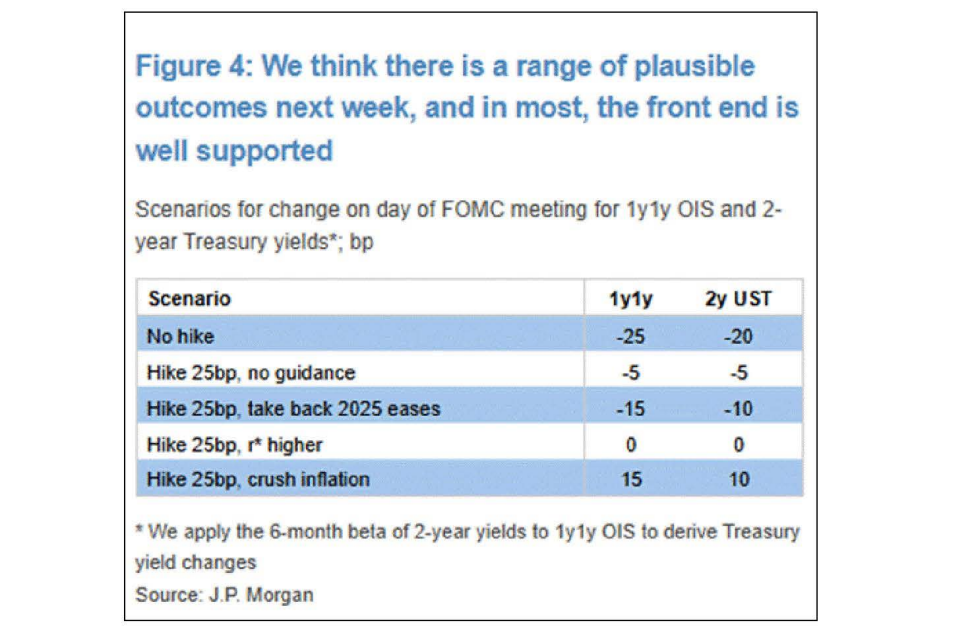
NO HIKE
A very low probability event, as inaction risks institutional credibility, and would make the reaction at the July FOMC meeting appear pale in comparison. In this event, we think 1y OIS rates (as a representation of the market's terminal Fed policy expectations) likely decline 25bp, which, using the observed sensitivity of Treasury yields to policy expectations in recent months, likely translates to a 20bp decline in 2-year yields.
HIKE, NO GUIDANCE
The FOMC raises rates 25bp to address above-target inflation, but Warsh offers no forward guidance. This ambiguity could lead to a modest decline in front-end rates.
HIKE, GUIDE TOWARD UNWINDING 2025 EASES
Given the Chair’s view that labor markets are at full employment, he indicates the 75bp of risk management cuts in 2025 were unnecessary, and the front end converges temporarily toward pricing in 75bp of total hikes.
•HIKE, R* IS HIGHER
The Chair admits policy is not restrictive and also admits that large-scale AI investment could drive productivity higher, resulting in higher trend growth and a higher neutral policy rate. Markets seem somewhat priced for this outcome, though 1y1y is back near its cycle highs and longer-dated forward expectations have eclipsed their 2023 highs, indicating markets believe in higher for longer, likely due to structural changes to the US economy (Figure 4). Given that perceptions of neutral tend to evolve slowly over time, we do not think the front end would move much, but there is room for longer-dated forwards to rise further.
HIKE, CRUSH INFLATION
To borrow Bruce Kasman’s analogy, the Fed moves from a forgiving, New Testament Committee to a more vindictive, Old Testament central bank as it commits to quickly bringing inflation back to target, allowing markets to price in a higher terminal rate, but longer-dated forward OIS rates likely decline as markets interpret the Fed as being willing to sacrifice growth and labor markets to restore price stability.
Overall, we [Jay & team] are not willing to attach probabilities to these outcomes, but the 'No Hike’ and 'Crush Inflation’ scenarios appear less likely than the other three outcomes in our mind, which could help the 2-year sector find firmer footing next week.