Standard Charted on FOMC: Hiking is the wrong choice - FJElite
The correct Fed policy decision in our view is straightforward - stay on hold until the noise from tariffs and data revisions dissipates. It is very likely that core inflation is overestimated. Tariffs are having a significant but uncertain upward effect on core PCE inflation. The Commerce Department’s comprehensive GDP revisions are likely to lower recent inflation estimates slightly. Core inflation is not moving decisively in either direction. From a risk-management perspective, the FOMC should allow data to settle before determining whether a hike is necessary. It could open the door to a 50bps hike if subsequent data supports the hawkish case. By contrast, reversing a premature hike would damage credibility and be seen as a very unsteady hand on the tiller.
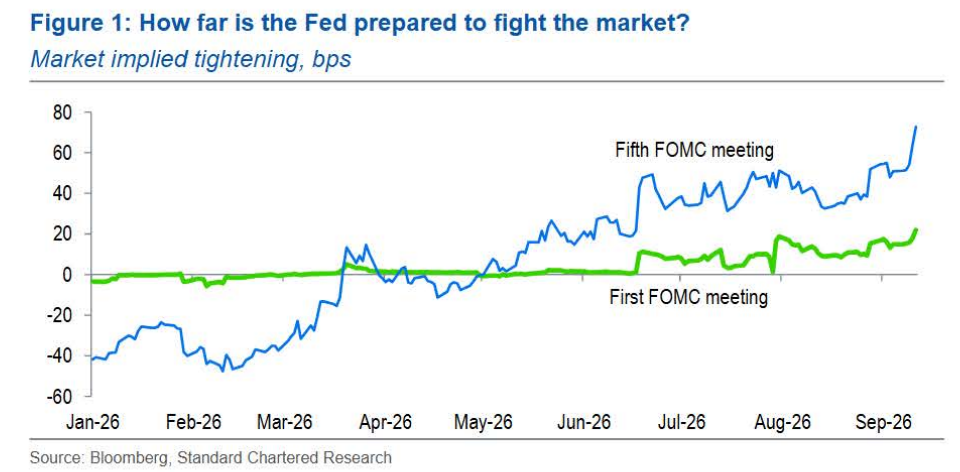
Fed funds futures are pricing in an 88% probability that the FOMC will hike by 25bps and now prices 74bps of hikes by March (Figurei). The market has priced 35bps of added hikes by March off Warsh’s Jackson Hole comment "We must be confident that underlying inflation is moving to our objective, clearly and at sufficient speed" and ignored Warsh’s emphasis on underlying inflation - "We want to gauge whether underlying inflation is rising, falling, or stuck in place." The data may look very different in a couple of months.
Even if a hold is justified, we see a clear risk that an on-hold decision hurts the long end of the UST curve and the USD. It is a big rates repricing to absorb and could reignite doubts around Chair Warsh’s inflation-fighting rhetoric that emerged after the 29 July FOMC meeting. This episode of USD weakness does not affect our medium- term view of USD strength, but the rates moves could lead to a sharp, albeit temporary downward USD move. The short end might not see much selling pressure, as more than three 25bps hikes are already priced in over the next 12 months, setting a high bar for the dot plot and Warsh’s press conference to out-hawk the market. If the Fed hikes as now priced, there could be an added boost to Warsh’s credibility, stabilising long-end yields and the USD.