Goldman Sachs: Gasoline Now Offers More Upside Than Diesel - FJElite
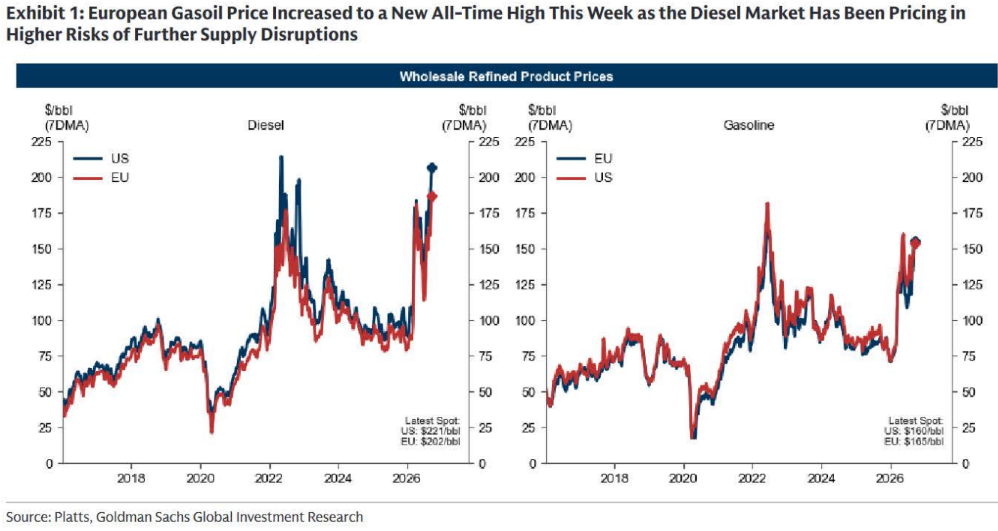
Diesel prices remain close to record highs in the US and Europe as the halt of the East-West pipeline adds further pressure to refinery crude supplies. With diesel already pricing in a large geopolitical premium, the long European diesel timespread recommendation is being closed after a potential gain of around $11/bbl, or 45%. Refined products are still seen as an effective hedge against further escalation, but the preferred exposure has shifted to summer European gasoline.
The main reason is that refiners are prioritising diesel output at the expense of gasoline, rapidly tightening gasoline supply. European June 2027 gasoline prices have risen much less than diesel, leaving more room for upside. US diesel yields have run above seasonal norms while gasoline yields have lagged, OECD gasoline output has fallen more than diesel output, and global gasoline exports are down 24% year-on-year. With gasoline prices still less elevated, further refinery disruption from the Middle East or Russia-Ukraine conflicts could produce sharper upside in gasoline than in diesel.