Goldman Sachs on Diesel - FJElite
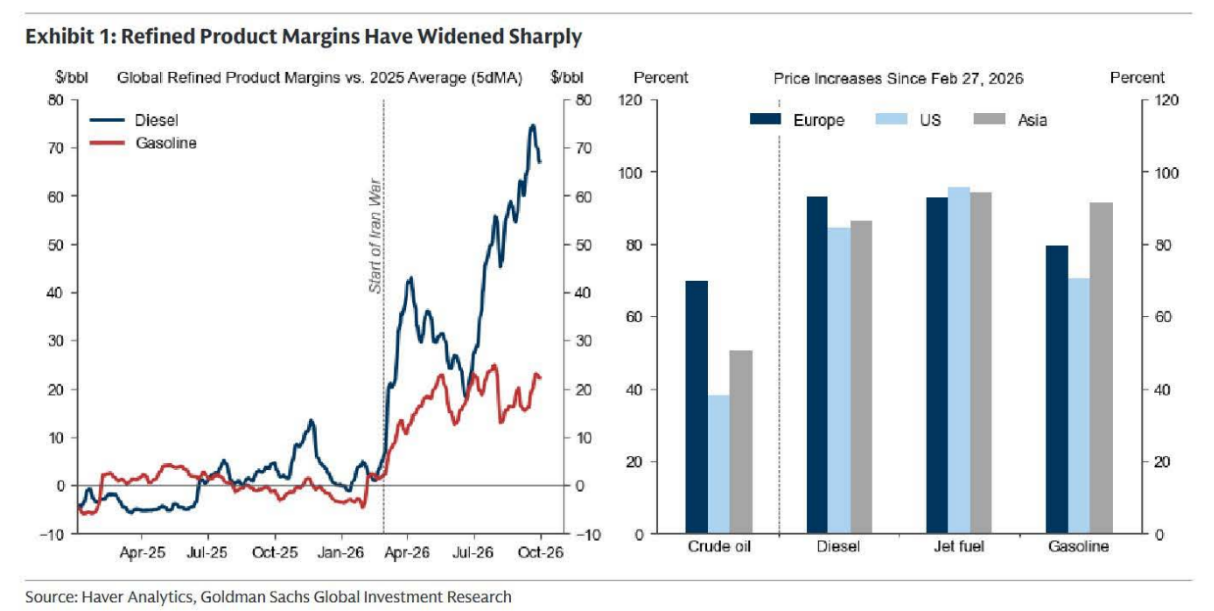
- Refined product margins have widened significantly since March. Diesel has been especially affected, reflecting highly inelastic demand due to its importance in industrial supply chains and ongoing strikes on refineries in the Middle East and Russia. Wholesale prices have increased by over 90% in Europe and over 80% in the US and Asia since the start of the war in Iran (Exhibit 1).
- In the very near term, a US diesel ban would put downward pressure on prices in the US, with our commodities team estimating a $0.25/gallon price reduction (or just under 4% of the current price) per week of export bans, implying a modest 2-3bp drag on headline US inflation after a month and a 4-5bp drag after two months. But this small decline in inflation would likely reverse and ultimately turn inflationary after roughly two months, since our commodity strategists estimate that each week of a diesel export ban would raise US retail gasoline prices by $0.3/gallon per week once diesel storage capacity is exhausted after 9-10 weeks.
The upside to gasoline prices would be smaller if refiners can switch more from diesel to gasoline or if diesel demand rises sharply. But gasoline accounts for a much larger share of the consumption basket, so the net impact would most likely be inflationary after two months. Core inflation impacts would likely remain small but negative for at least 12 weeks, reflecting the relatively greater importance of diesel as an intermediate input in production and delayed pass-through from producer costs to consumer prices.