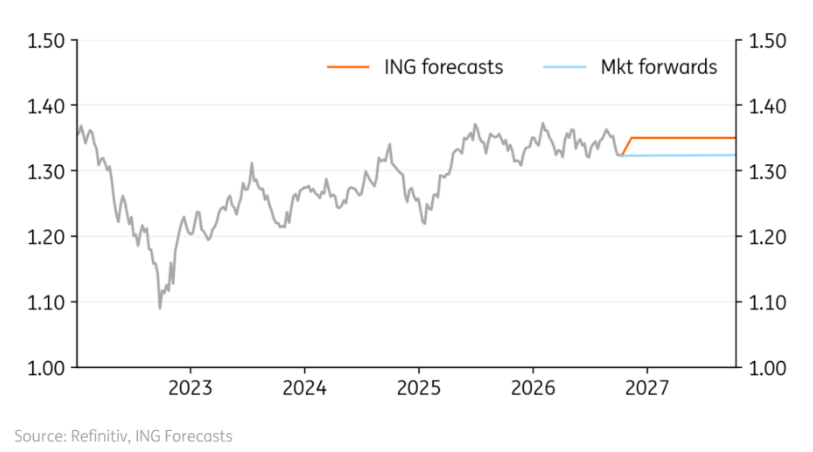
ING: GBP/USD - FJElite
With energy prices staying higher for longer, it increasingly looks like the Bank of England might hike at its 5 November meeting. If it does, we suspect another hike will be coming in February - taking the policy rate to 4.25%. Central to the BoE is inflation approaching 4%, a level where BoE research has found that second-round inflation effects become greater.
The Bank delivering on expectations of a rate hike should be a sterling positive - cementing its status as a G10 high-yielder.
28 October is a UK event risk in the form of Prime Minister Andy Burnham's first budget. Cost of living support measures should be announced, but we expect them to be funded, avoiding a Gilt market sell-off.